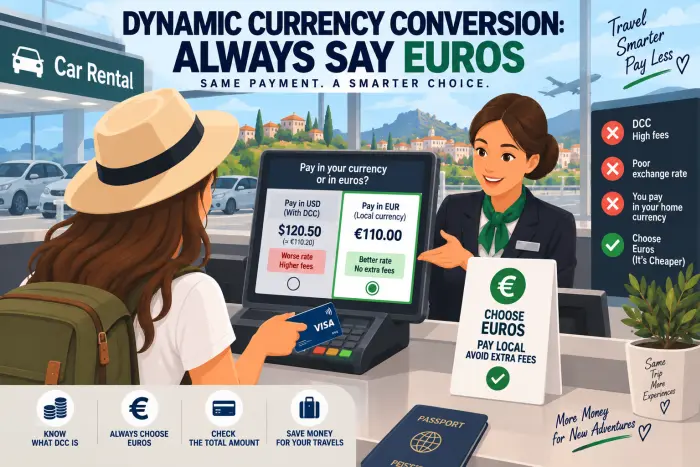
“Would you like to pay in euros or in dollars?” sounds like a courtesy, and at nearly every car rental counter in Italy, it’s actually a quiet way to charge you more than you’d pay otherwise. Understanding dynamic currency conversion — and simply knowing the one right answer to give — is one of the easiest ways to avoid losing money on a rental you’ve otherwise done everything right to book well.
What Dynamic Currency Conversion Actually Is
Dynamic currency conversion, usually shortened to DCC, is a service offered by the merchant — in this case, the rental counter — that lets you see and pay your bill in your home currency instead of euros. It sounds convenient: you know exactly what you’re paying in dollars, pounds, or whatever currency your card bills in, with no guessing about the exchange rate. The catch is that the exchange rate used for that conversion is set by the merchant or their payment processor, not by your card network, and it’s reliably worse than the rate you’d get if the charge simply ran in euros and your own bank or card network converted it afterward. On top of the worse rate, a separate conversion fee is often layered in as well, sometimes disclosed clearly and sometimes buried in fine print on the receipt.
Why This Shows Up So Often at Rental Counters Specifically
Car rental transactions tend to be larger than a typical tourist purchase, which makes DCC especially costly here compared to, say, a coffee or a souvenir — a markup of even a few percentage points on a full week’s rental plus insurance and fuel adds up to real money, not a rounding error. Rental counters, along with hotels and higher-end restaurants that see regular international customers, are also simply set up for it more often than a local grocery store or fuel station would be, since the payment terminal itself needs specific configuration to offer the choice.
How to Spot It and Say No
The moment it usually comes up is either during loyalty program enrollment (some sign-ups ask you to pre-select a currency preference) or at the counter itself when the final charge is processed. If you’re handed a signature slip or shown a screen displaying an amount in your home currency rather than euros, that’s DCC being applied by default — say clearly that you’d like to be charged in euros instead, and ask them to redo the transaction. If a staff member says the currency can’t be changed, it’s worth pushing back once, since this is very often a default setting on the terminal rather than a genuine limitation — but if they genuinely can’t change it in the moment, note it and raise it with your card issuer afterward rather than assuming there’s nothing to be done.
| What you see | What it means | What to do |
|---|---|---|
| Receipt or terminal shows an amount in euros | Standard conversion, handled by your card network at a normal rate | Sign as-is, no action needed |
| Receipt or terminal shows an amount in your home currency | Dynamic currency conversion is being applied | Ask to switch to euros before signing |
| A loyalty enrollment form asks for a “preferred currency” | An opt-in DCC setting for all future transactions with that company | Select the local currency or decline to set a preference |
| Fine print showing a conversion rate or markup percentage | The actual cost of accepting DCC | Compare it against your card’s published exchange rate if you want the exact difference |
The Deposit Hold Matters Too
It’s not just the final rental charge — the security deposit hold placed on your card at pickup can also be run through DCC if you’re not paying attention, meaning a temporarily larger hold on your account than necessary during your trip. The same rule applies: if you’re asked which currency to hold the deposit in, choose euros.
💸 Italy Car Rental Sale – Up to 40% Off Today
Find the cheapest car rental deals in Rome and across Italy. Compare prices instantly and lock in your discount before it's gone.
Your Card’s Own Foreign Transaction Fee Matters More Than You’d Think
Whether DCC is even a meaningful concern for you depends partly on your specific card. If your card charges its own foreign transaction fee (commonly 1-3%) on top of paying in euros, that’s a separate cost layered onto an already-correct decision, and it’s worth checking before your trip whether your card has one. Many travel-oriented credit cards waive foreign transaction fees entirely, in which case paying in euros with no DCC is close to the best possible outcome available to you. If you don’t know offhand whether your card charges this fee, it’s worth a quick look at your card’s terms before you travel rather than discovering it on your statement afterward.
A Few Questions Worth Asking
Is dynamic currency conversion illegal? No — it’s a disclosed option in most cases, not fraud, which is exactly why it persists despite being a bad deal for the customer almost every time. The issue isn’t legality, it’s that accepting it almost never benefits you.
What if the counter says euros aren’t an option? Ask again, and if they genuinely insist, note the details and raise a dispute with your card issuer if the final charge doesn’t match what you expected — most issuers are familiar with this pattern and can help.
Does this apply to ATM withdrawals too, not just the rental counter? Yes, the same principle applies at ATMs across Italy — if you’re asked whether to convert to your home currency at withdrawal, decline and take euros at the standard rate instead.
Is there ever a case where DCC actually makes sense? Rarely, and mainly if you have no idea what the correct exchange rate should be and value the certainty over the cost — for the vast majority of travelers, declining it and paying in euros is the better default choice every time.
Whichever car rental company you book with, the currency question at the counter is worth exactly one clear answer: euros, every time, no exceptions worth making.